Article content
When evaluating a scaffolding business, test whether its operating records explain the equipment, live projects, customer commitments, and unresolved work you would inherit. A polished summary is useful, but the underlying evidence must support it. The operational review should show how the business functions when the current owner is not personally explaining every detail.
This guide is an operational evidence checklist for prospective buyers and their advisers. It does not provide a valuation, recommend a transaction, or replace financial, legal, tax, or technical due diligence. Use qualified professionals to assess those areas and connect their findings with the operating evidence described here.
Start with the actual business model
Clarify what the company sells, which customers it serves, and how work moves from enquiry to closeout. Determine whether its operations rely on owned equipment, hired-in material, subcontracted services, or a mixture. The record requests should reflect the actual service model.
Ask management to walk through a recently completed project and a current project. Compare the explanation with the documents. The objective is to understand ordinary operations before focusing on exceptional cases or headline claims about growth.
Identify responsibilities concentrated in the owner or a small number of employees. A business can have capable staff while still depending on one person's memory for pricing history, stock locations, or customer commitments. Document those dependencies so the transition plan can address them.
Test the equipment register against reality
Request the item catalogue, location balances, ownership information, and the movement records supporting selected quantities. Use competent operational assistance when evaluating the equipment itself. A spreadsheet quantity does not establish ownership, physical presence, condition, or suitability.
Select a sample across yard stock, active sites, and material with unresolved movements. Trace each selected balance back through deliveries, transfers, returns, and adjustments. Then compare the records with appropriate physical verification or other supporting evidence.
Keep different uncertainties separate. Missing ownership evidence, a counting discrepancy, and a condition concern are not the same issue. Record the nature of each finding and assign the relevant specialist or responsible person to assess its implications.
Distinguish owned and hired-in material
Review how the company identifies equipment belonging to other suppliers. Ask for the relevant supplier references and outstanding positions. Material on a customer site may create return obligations even if it does not appear in a simple owned-asset total.
Test a project containing mixed ownership. The records should explain what is present, where it came from, and what must eventually return to each source. If the distinction relies on informal knowledge, document the reconciliation work required before relying on the balances.
Ask the appropriate advisers to assess contractual obligations and their treatment in the proposed transaction. The operational task is to provide a clear inventory of evidence and unresolved questions rather than assume that every visible component belongs to the seller.
Reconstruct live project positions
Request a list of active projects with current scope, responsible contacts, relevant dates, material balances, and unresolved changes. Define what active means in the seller's records. A job can be operationally finished while still carrying equipment or commercial issues.
Sample projects at different stages. Include a recent start, a long-running job, and one approaching closure. Trace the accepted scope to actual movements and current obligations. This helps reveal whether the project list is a working control or merely a sales summary.
Identify inconsistencies between systems. The scheduling tool, inventory record, and accounts process may use different statuses or references. Record how management reconciles them and whether the reconciliation can be repeated by someone outside the current team.
Examine changes and disputed work
Ask how customer changes are requested, reviewed, approved, and recorded. Select examples involving additional work, extended duration, or a changed collection plan. The current project position should be supported by identifiable instructions rather than an unexplained adjustment.
Review unresolved requests separately from approved changes. A pending instruction should not be presented as a settled commitment simply because work has started. Have the relevant advisers assess commercial implications where required.
Look at how disputes are documented and followed up. A useful record includes the issue, supporting evidence, responsible person, and current action. The aim is not to assume that every dispute indicates poor management, but to understand the work and uncertainty that remain open.
Inspect return reconciliation and closure
Request recent return records and the corresponding site balances. Check whether counted receipts are distinguished from expected collections. A collection booking does not establish that all equipment has returned or that the recorded project balance is correct.
Review old outstanding balances. Ask what actions have been taken and which differences remain unresolved. Separate actual missing material from timing differences, incomplete documents, and approved adjustments. Those categories require different follow-up.
Test the project closure procedure. A reliable process identifies outstanding equipment, incomplete transfers, pending changes, and missing records before the relevant operational position is closed. If one generic status hides several unfinished processes, document the resulting uncertainty.
Evaluate the quality of management information
Ask for definitions behind key reports. Available stock, utilization, completed jobs, and overdue returns can mean different things in different businesses. A comparison is meaningful only when the calculation, population, and period are clear.
Trace a reported number to its underlying records. For example, select one site balance or return-aging figure and reproduce it from the events. This reveals whether the report is supported by consistent data or depends on manual adjustments that are difficult to inspect.
Check how missing data is treated. A blank value should not silently become zero, and an unverified balance should not be presented as confirmed. Honest uncertainty is more useful to a buyer than precise-looking information whose limitations are hidden.
Understand the team and operating dependencies
Map the responsibilities for planning, yard control, site coordination, document administration, and commercial follow-up. Ask who provides cover during absence. The transition plan needs to account for practical knowledge and authority, not merely job titles.
Observe a routine handoff where appropriate. Can the yard retrieve the current order without calling the owner? Can an administrator find a delivery record and explain a correction? These tasks provide evidence of whether the operating process is shared across the team.
Review training and procedure documentation with the responsible people. A written process is valuable only if it reflects actual work. Identify areas where instructions are outdated or where the business relies on informal habits that a new owner would need to understand.
Review technical and safety administration with specialists
Have competent professionals assess the relevant technical systems, responsibilities, records, and practices. An operational buyer should not infer adequacy from the existence of a folder labeled compliance or a software dashboard showing completed tasks.
Ask how records are linked to the correct project or structure and how revisions are controlled. Determine whether the responsible people can retrieve current information and explain historical changes. Administrative traceability supports the specialist review but does not replace it.
Use authoritative requirements for the jurisdictions and work involved. Do not apply a generic checklist from another market as though it establishes the business's obligations. Record the scope and limitations of each professional review alongside its findings.
Inspect software access and data portability
List the applications used for operations, accounting, documents, and customer information. Identify account ownership, administrators, integrations, and access arrangements. Have advisers review contractual transferability where relevant to the proposed transaction.
Request sample exports containing project identifiers, item codes, movements, dates, and supporting references. Include documents and attachments. A usable export should allow an informed reviewer to understand the records without relying entirely on the existing interface.
Check whether important information exists outside the principal system, including private spreadsheets or individual inboxes. The transition plan should identify those dependencies and provide an authorized way to preserve necessary business records while respecting applicable access and privacy obligations.
Create a findings register with evidence
For each issue, record the observation, source, affected projects or records, responsible reviewer, and next action. Distinguish confirmed findings from questions still awaiting evidence. This keeps the operational review useful to the wider due-diligence team.
Avoid translating every issue directly into a price adjustment yourself. Financial and legal advisers need the operational facts and their limitations to assess transaction implications. Your role is to make those facts inspectable and prevent unsupported assumptions from entering the decision.
Agree what must be resolved before completion and what belongs in a post-transition plan with the appropriate advisers. A practical transition list might include verified opening balances, named process owners, access handover, and reconciliation of selected live projects.
Plan the first operational improvements
After the transaction decision and relevant approvals, prioritize improvements around the most consequential information gaps. Introducing new software immediately is not always the first step; unclear item codes or unresolved ownership need business decisions before migration.
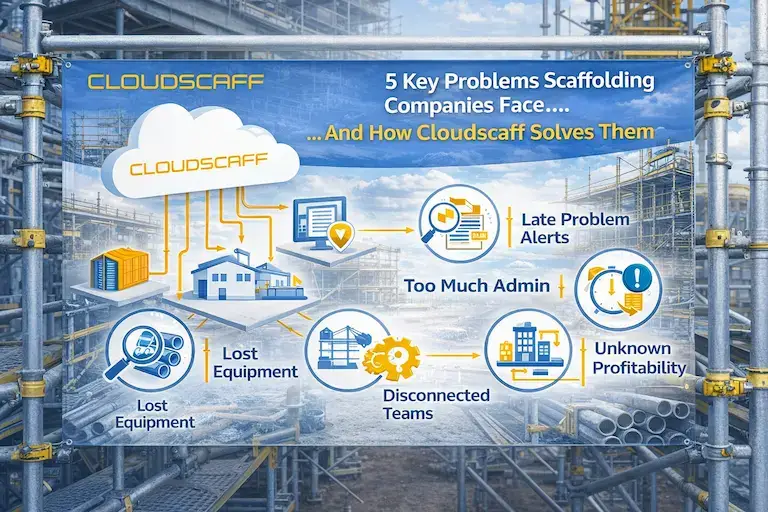
If a system change is appropriate, evaluate CloudScaff's features using the actual workflows uncovered during review. Confirm the migration scope, responsibilities, and required connections directly. Preserve an accessible history so improvement work does not erase the evidence needed to understand inherited projects.
Frequently Asked Questions
What is the most useful operational test?
Trace selected live and completed projects from accepted scope through movements, changes, returns, and closure. Compare the records with the physical and commercial evidence using the appropriate specialists.
Can an equipment spreadsheet establish asset value?
No. It is one source of information. Ownership, physical verification, condition, and valuation require appropriate evidence and professional assessment; a recorded quantity alone does not establish those facts.
Should we replace the software immediately after buying?
First understand the records, dependencies, and unresolved balances. If replacement is appropriate, plan a controlled migration that preserves history and assigns clear responsibility for the opening position.
Conclusion
Operational due diligence tests whether the business can explain what it owns, what it has committed, and what remains unresolved. Build a traceable evidence register and use it alongside qualified financial, legal, and technical review.